Capital, Engineered to Endure.
Life insurance advisory to Canada's leading enterprise families and the advisors who guide them.
The Inflection Point
There is a point in the life of every significant enterprise when the question stops being how to grow capital and becomes how to keep it, intact and under your control, as it moves between hands, entities and generations.
A sale. A succession. A freeze. The death of a partner the business is bound to buy out. In each, the structure put in place beforehand either compounds in your favour for decades or quietly works against you.
Most planning is built for the years of accumulation. Very little is built for these moments, and almost none of it early enough.
Before the Moment
By the time a sale, a succession or a death arrives, the options have already been set. Insurability, pricing and structure are decided years in advance, at the health and age of the day the coverage is underwritten.
For most owners, the capital to fund it already exists, sitting as surplus inside the corporation and taxed every year it waits. The question is whether it is repositioned deliberately, or left for the estate to sort out.
When the liability that lands on death runs into the millions, generic advice stops being useful.
The families that endure decide early.
We Answer to One Party
We are independent and bound to no insurer. We are retained to get the structure right, which sometimes means telling you, and your advisors, that life insurance is not the answer.
What We Build
Liquidity available precisely when an estate, a shareholders’ agreement or a transaction demands it: for the tax that lands on death, a partner’s shares, the fair treatment of heirs who will not all run the business, or the protection of what has been built. Capital that funds the obligation without sitting idle against it, and reaches the next generation intact. And where the family intends it, a philanthropic legacy that outlasts everyone at the table.
When the work is done well, the transition looks effortless.
Who We Work With
Business families planning succession and estate continuity. Owners of mature operating companies holding or building substantial surplus. Private holding structures repositioning capital across entities and jurisdictions. Founder-operators approaching or recovering from a liquidity event.
And the accountants, tax counsel, deal advisors and family office leaders who advise them.
How We Work
Every engagement begins with a private conversation about the business, the structure, and what the capital is ultimately for. If there is a gap worth addressing, we map the full structure, model the strategy, and review it with your accountant and counsel before anything is implemented. If there isn’t, we say so.
We also review existing policies regularly, to ensure each remains structured for the purpose it was designed to serve.
We hold established relationships with Canada’s major carriers and their underwriting teams, and the capacity to place large, complex cases, including those that require reinsurance.
Begin a Conversation
We work with a small number of families and their advisors at any one time. If the timing is right, it becomes clear quickly. If it isn’t, we will say so.
Every engagement is confidential. Engagements begin by introduction or private conversation.
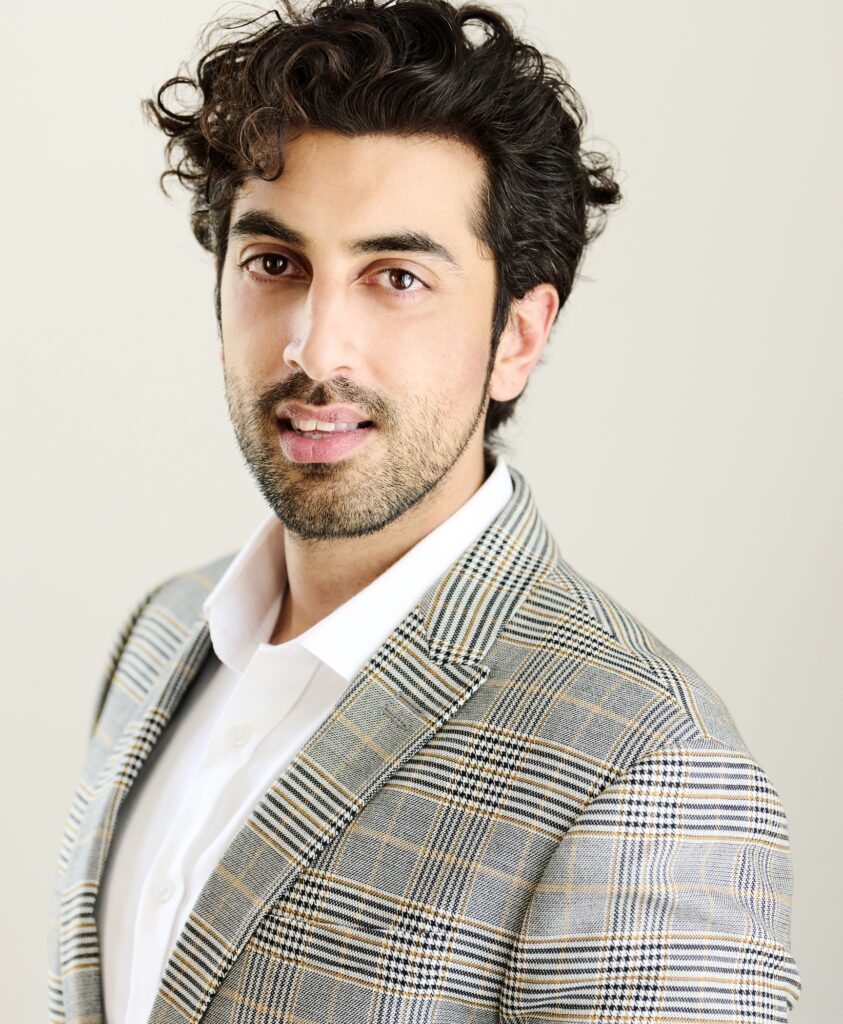
FOUNDER & PRINCIPAL
Shannon Gill
A decade advising Canadian business owners and families. His work is at the intersection of insurance, corporate finance and estate planning. He works alongside the accountants, lawyers and advisors already at the table, and designs around the family’s multi-generational and philanthropic intentions.
“A transition in capital is never only financial. What's needed at that point is not more options. It's someone who sees the entire board, and who designs for permanence rather than just the transaction in front of them.”
GILKO CAPITAL
Gilko Capital does not provide tax or legal advice. © 2026 Gilko Capital. All rights reserved. E&OE. Privacy Policy Disclosure